
Texas Finalizes Landmark Mandatory Right to Appraisal Rules, Delivers Historic Consumer Protection Victory
News originally published by
EIN Presswire
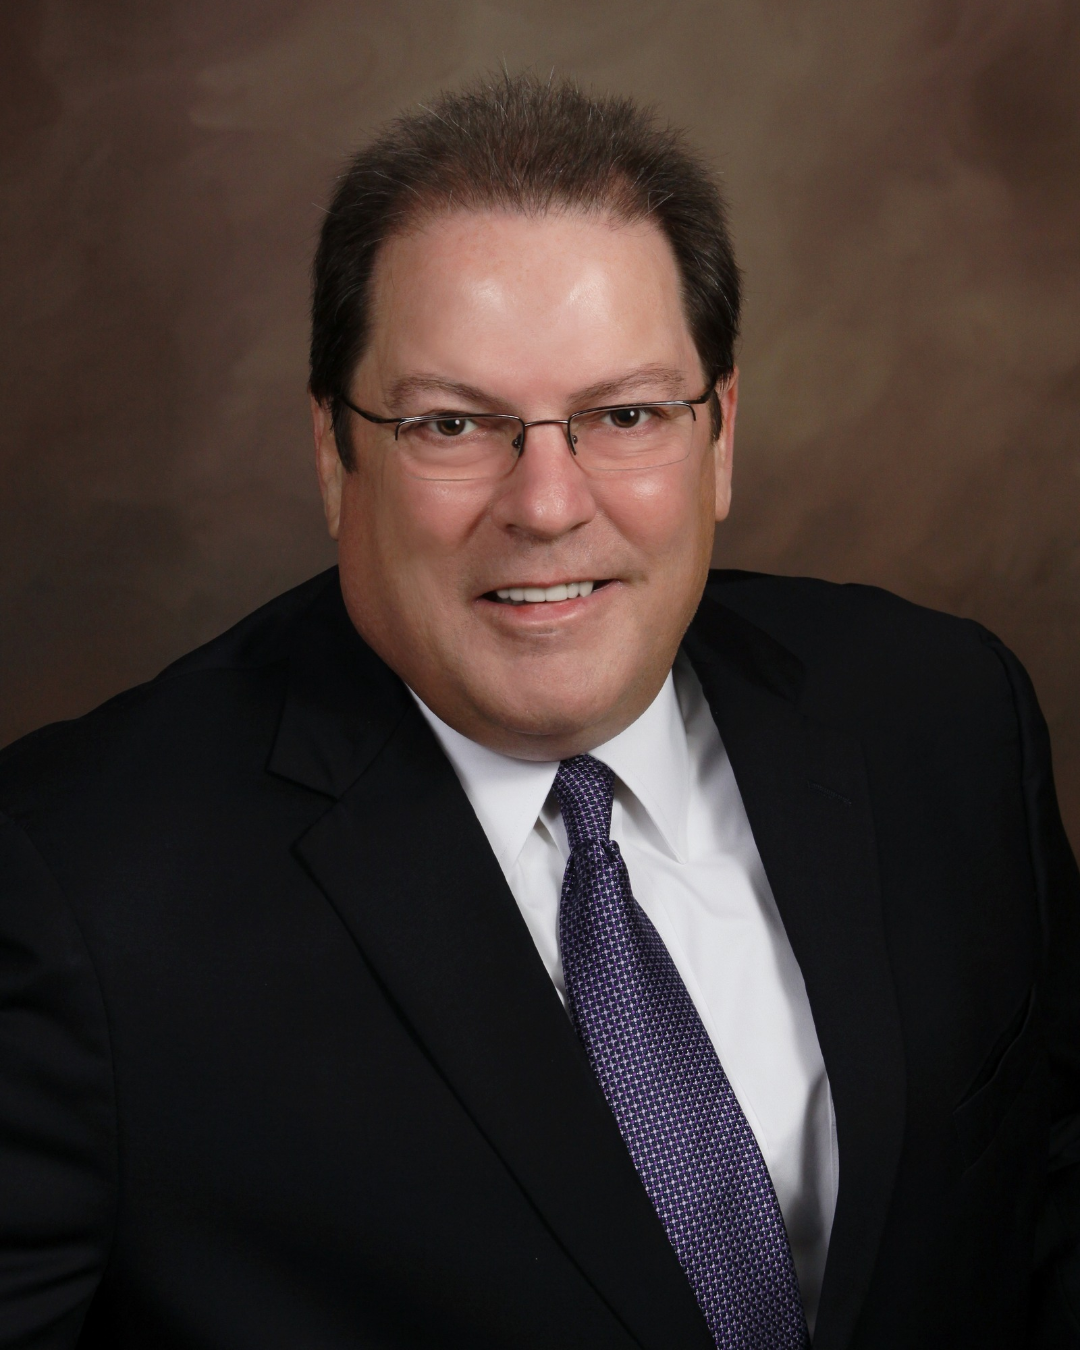
Robert McDorman, founder and president of Auto Claim Specialists and longtime advocate for Texas policyholders' Right to Appraisal

Robert McDorman (right) testifies before the Texas Senate Committee on Business and Commerce as part of his decade-long campaign to strengthen policyholder appraisal rights.

Robert McDorman, founder and president of Auto Claim Specialists, addresses Texas lawmakers during a legislative committee hearing on insurance consumer protections.
Decade-Long Battle by Automotive and Consumer Advocates Reshapes Texas Insurance Landscape and Levels Playing Field for Policyholders
The finalized rules establish the regulatory framework governing the Mandatory Right to Appraisal (RTA) for personal automobile and residential property insurance claims, putting into practice the protections unanimously approved by the Texas Legislature in 2025. By establishing standardized procedures, defined timelines, minimum qualifications for appraisal participants and consumer notification requirements, the regulations provide a structured process for resolving disputes over the amount of loss. The framework strengthens Texas policyholders' ability to challenge inadequate claim settlements and seek fair indemnification without resorting to costly litigation.
Robert McDorman, president and founder of Auto Claim Specialists – whose relentless defense of policyholders has earned him the nickname “The Appraisal Saint” – believes the finalized framework represents a significant step toward restoring balance between insurers and policyholders by establishing a clearer, more consistent process for resolving disputes over the amount of loss.
"This is one of the most significant shifts in Texas insurance regulation that I've seen over my career,” McDorman says. "For too long, policyholders have faced an uphill battle when challenging inadequate claim settlements. These rules help level the playing field by establishing a clear, enforceable process that gives Texas consumers a meaningful opportunity to exercise the protections the Legislature intended."
Rather than serving as administrative housekeeping, the finalized regulations establish the operational framework necessary to make Mandatory Right to Appraisal meaningful in practice. Beyond defining procedures, timelines and qualifications for appraisal participants, TDI incorporated significant revisions during the rulemaking process that strengthen policyholder protections and address concerns raised by Auto Claim Specialists and other consumer advocates.
Among the most consequential changes is a revision to the umpire-selection process – a central concern raised by McDorman throughout the rulemaking proceedings. Under TDI's original proposal, insurers could include vendor-based umpire-selection mechanisms in their policies before a dispute arose, potentially allowing insurer-selected vendors to influence the appointment of a supposedly neutral decision-maker. McDorman warned that vendors seeking placement on carrier-approved lists face an inherent institutional incentive to favor insurers, raising serious questions about the independence and impartiality of the process.
"The umpire rule needs to be crystal clear that judicial appointment must always remain an available option when appraisers cannot agree on an umpire," McDorman stated during the rulemaking phase. "Most policyholders lack the resources or sophistication to challenge a carrier-embedded umpire-selection process, making it critical that insurers cannot force consumers into a mechanism they did not choose."
Following extensive public comments, TDI revised §5.9806(b)(3) to ensure that only the policyholder may invoke an independent-vendor umpire-selection option. Although insurers may still include such vendors in their policies, they cannot unilaterally require policyholders to use that mechanism. The adopted rules require insurers to include judicial appointment as an available option when the parties' appraisers cannot agree on an umpire, preserving access to a court-appointed decision-maker rather than forcing consumers into an insurer-established vendor process.
TDI also made a significant change to the deadline for demanding appraisal in personal automobile claims. The original proposal generally required appraisal to be demanded within 120 days after the claim was accepted or rejected. Under the adopted §5.9806(a), that deadline is instead tied to the expiration of the policy's limitations period for filing suit, potentially giving policyholders substantially more time to challenge disputed claim valuations. The final rules establish separate, more restrictive deadlines once litigation has begun, making it important for consumers to understand their rights before initiating legal action.
Beyond these revisions, the regulations establish consistent procedures for conducting appraisals, including deadlines for appointing appraisers, selecting umpires and reaching an award. For personal automobile claims, each party generally must appoint an appraiser within 20 days of an appraisal demand, and appraisers have 40 days to attempt agreement on the amount of loss. When an umpire becomes involved, an appraisal award must be issued within 180 days of the original demand; however, parties retain the ability to modify deadlines by written agreement. The rules also require insurers to notify policyholders of their appraisal rights when issuing claim acceptance or rejection notices, helping ensure consumers understand how to exercise these protections.
Together, these provisions are expected to bring greater consistency, predictability and fairness to the appraisal process, providing policyholders with a more accessible alternative to costly litigation when disputes arise over the amount of loss. For Texas families, the stakes extend beyond the settlement itself: inadequate claim payments can force consumers to cover repair costs out of pocket, delay necessary repairs or make compromises that could affect vehicle safety.
Beyond procedural improvements, advocates expect the finalized regulations to return hundreds of millions of dollars to Texas consumers, as historical appraisal data demonstrates that the process frequently results in substantially higher claim payments than insurers' original offers when legitimate disputes exist. According to TDI’s own “Appraisal Experience Data Call Report,” approximately 98% of personal automobile appraisals resulted in awards exceeding insurers' initial settlement offers, reinforcing longstanding concerns about inadequate claim payments and the importance of providing policyholders with an effective mechanism for challenging disputed valuations.
Research conducted by Auto Claim Specialists found that appraisal increased settlements by an average of $6,111 for repair claims and $4,044 for total losses. Building upon those findings, McDorman’s analysis, “Potential Insured Financial Impact of the Mandatory Appraisal Law in Texas,” estimates that if just 10% of eligible Texas personal automobile claimants exercise their appraisal rights annually, the resulting increase in claim payments could reach approximately $337.8 million per year.
But for McDorman, those findings represent much more than numbers. "Every dollar represents a Texas family trying to restore their vehicle. When people aren’t fully indemnified, they're forced to pay out of pocket, delay necessary repairs or accept unsafe compromises. This has always been about protecting consumers."
He believes the regulations will also improve claim handling long before appraisal is ever invoked. "When insurers know there's a fair, enforceable appraisal process available, they're motivated to evaluate claims more accurately from the beginning. A credible dispute-resolution process benefits everyone by encouraging better claim practices across the board."
Although the regulations were finalized in 2026, the fight to restore meaningful appraisal rights in Texas began over a decade ago. When TDI approved State Farm's request to remove the Appraisal Clause from its Texas automobile insurance policies for repair procedure disputes in 2015, consumer advocates warned that the decision would significantly weaken policyholders' ability to challenge disputed claim settlements without resorting to expensive litigation.
Recognizing the long-term implications, McDorman, along with ABAT’s Burl Richards and Texas Watch Executive Director Ware Wendell, helped organize a sustained, data-driven campaign to restore and protect appraisal as an accessible dispute-resolution mechanism. Throughout the process, McDorman met with TDI officials on multiple occasions and testified eight times before legislative committees, presenting research documenting concerns about systemic under-indemnification in the insurance claims process. For a decade, he also authored “Ask the Expert,” a monthly column in Texas Automotive, using the platform to educate legislators, consumer advocates, attorneys, public adjusters and collision repair professionals about the Appraisal Clause and its importance to policyholders.
The campaign grew into a broad coalition of collision repair professionals, attorneys, public adjusters, consumer advocates and policyholders united around the need for meaningful appraisal protections. This legislative effort was heavily supported by Auto Claim Specialists’ lobbyist, Andrew “Drew” Graham of Graham Public Affairs, who helped lawmakers understand complex claims data and the practical consequences of restricting appraisal rights. His advocacy, alongside lobbyists Jacob Smith and Jesus Moreno of Longleaf Consulting, solidified the broad bipartisan agreement that paved the way for the implementation of these finalized administrative rules.
Their collective efforts ultimately resulted in the unanimous passage of Senate Bill 458 in 2025, authored by Senator Charles Schwertner (R-District 5) and sponsored in the House by Representative Jay Dean (R-District 7). But securing unanimous legislative approval was only part of the battle. McDorman and fellow advocates knew the next critical challenge would come during TDI's rulemaking process.
"The statute gave consumers the Right to Appraisal; the rules determine whether that right works effectively,” McDorman stresses.
As TDI developed the administrative framework, Auto Claim Specialists and other consumer advocates remained actively engaged, submitting formal comments and recommendations intended to strengthen consumer protections while preserving the Legislature's intent. Those recommendations included provisions addressing the independence of umpire selection, potential financial conflicts involving insurer-designated vendors, consumer costs, professional qualifications and regulatory enforcement. McDorman also urged TDI to preserve judicial appointment as a mechanism for resolving umpire-selection disputes rather than allowing insurers to establish vendor-controlled procedures that policyholders would have to overcome.
McDorman credits TDI for responding to those concerns with a significant revision to the final umpire-selection requirements. "For years, our conversations focused on helping regulators understand the challenges Texas consumers were facing. Throughout this process, the Department demonstrated a willingness to evaluate empirical data and consider recommendations from a broad range of stakeholders. They didn't simply hold public hearings – they listened. When we presented evidence showing why judicial appointment needed to remain an available option if appraisers could not agree on an umpire, TDI considered those concerns and revised the final rule. That's exactly how the regulatory process is supposed to work.”
Although not every proposed safeguard was incorporated into the final regulations, McDorman views the adoption of meaningful appraisal protections as the culmination of an extraordinary collective effort. "This victory belongs to a tremendous number of people; it wasn’t the accomplishment of one organization or one individual," he emphasizes. "ABAT stood beside us from the beginning, Texas Watch consistently championed consumers, and many collision repair professionals, attorneys, public adjusters and policyholders shared their experiences to help educate decision-makers. Legislators from both parties took the time to understand the issue instead of viewing it politically. We accomplished this together."
The persistence required to achieve that result, he adds, offers an important lesson about effective advocacy. "This victory results from ten years of consistent messaging. We didn't change our message because the facts never changed. We simply continued presenting the evidence until everyone understood why this mattered.”
Under the finalized regulations, the new appraisal requirements apply to personal automobile and residential property insurance policies delivered, issued for delivery or renewed in Texas on or after March 1, 2027. The implementation period gives insurers time to update policy language, obtain necessary regulatory approvals and incorporate appraisal notices into their claims procedures.
As the implementation date approaches, consumer advocates believe public education will become the next critical phase of the initiative. Although the legislation and regulations establish mandatory appraisal protections, many policyholders remain unfamiliar with the process or how it can help resolve disputes over the amount of loss without resorting to litigation.
Auto Claim Specialists plans to continue educating consumers, collision repair facilities, attorneys, public adjusters and insurance professionals about Mandatory Right to Appraisal and its role within Texas insurance law. "Our work isn't finished simply because the rules have been adopted," McDorman acknowledges. "Now, we have the responsibility to ensure Texans understand they have this protection available. Rights only matter if people know they exist."
For McDorman, the significance of the achievement extends beyond the regulations themselves. After a decade of challenging established insurance practices and advocating for stronger consumer protections, he believes the outcome demonstrates what sustained, evidence-based advocacy can accomplish. "We went up against incredible odds," he reflects. "The insurance industry possesses enormous financial resources, and for years, individual consumers simply didn't have the same voice. But persistence and facts matter. When you're willing to do the work, present credible evidence and keep fighting for the right reasons, meaningful change is possible."
Ultimately, he says, the measure of success will be its impact on Texas families. "This was never about defeating the insurance industry. It was about protecting Texas families. Because lawmakers listened, because TDI remained open-minded throughout the process and because so many organizations and individuals refused to give up, Texas consumers won! These rules will help ensure fairer settlements, safer repairs and stronger consumer protections for generations to come. That will make a difference for real people, and that’s what makes all our hard work worthwhile."
The completed framework sends an important message well beyond Texas, according to McDorman. "Other states are watching what happens here. Texas has demonstrated that protecting consumers and creating clear, consistent claim procedures are not mutually exclusive. In fact, they strengthen the insurance system by creating greater accountability, predictability and public confidence."
With the adoption of Division 4, a decade-long effort to restore meaningful appraisal protections has reached a defining milestone. The resulting framework establishes clearer procedures, minimum qualifications, consumer notification requirements and protections surrounding the selection of independent appraisal participants, creating a more consistent process for resolving disputed insurance claim valuations.
As Texas prepares for implementation in March 2027, the result is a stronger, more balanced insurance claims system that reinforces legislative intent and restores meaningful protections for policyholders. With legislators from several other states already reaching out to McDorman for data and guidance on developing similar consumer protection statutes, the Texas framework is also emerging as a potential model for insurance reform well beyond the Lone Star State.
###
Auto Claim Specialists is a national public insurance adjuster agency dedicated to ensuring consumers receive a fair settlement on their auto claims. Founded in 2017 by consumer advocate Robert McDorman (“Ask the Expert”), Auto Claim Specialists seeks to hold insurers accountable for fully indemnifying their policyholders for damages suffered by establishing the true value of losses. More information can be found online at autoclaimspecialists.com or by calling 817-756-5482.
Robert McDorman
Auto Claim Specialists
+1 817-756-5482
Visit us on social media:
LinkedIn
Instagram
Facebook
TikTok
Legal Disclaimer:
EIN Presswire provides this news content "as is" without warranty of any kind. We do not accept any responsibility or liability for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this article. If you have any complaints or copyright issues related to this article, kindly contact the author above.
